The $250 Billion Creator Economy Gap: Why India Has 50 Million Creators and Almost No Creator Economy
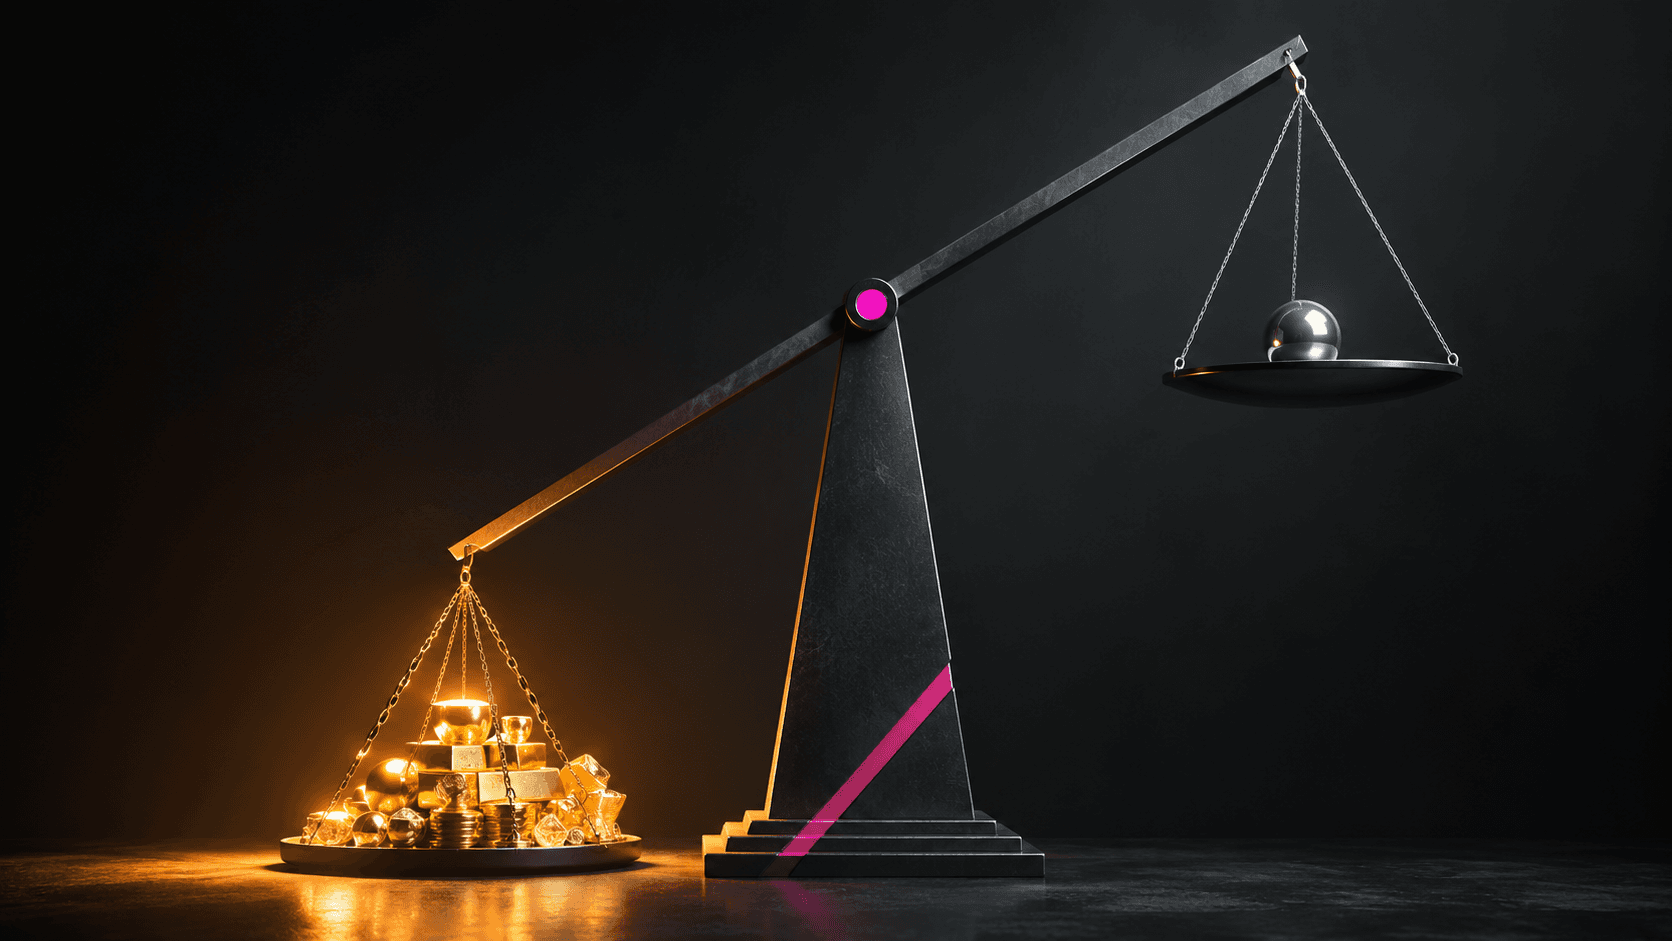
The number that explains the opportunity
United States creator economy: approximately $250 billion.
India creator economy: approximately $0.4 billion.
Number of content creators in the US: roughly 50 million.
Number of content creators in India: over 50 million.
Pause on those last two lines. The creator populations are comparable. The economic output is 625 times different.
This is not a talent gap. This is not a content quality gap. This is an infrastructure gap. The plumbing that converts creator content into creator income does not exist in India in any meaningful form.
Why the gap exists: the infrastructure stack
The US creator economy did not emerge from talent alone. It emerged from a stack of interconnected infrastructure that was built over about fifteen years: monetisation platforms with meaningful revenue share, brand partnership marketplaces that connected creators to advertisers efficiently, creator fund mechanisms, merchandise infrastructure, payment systems that worked seamlessly, subscription tools, live commerce capability, and a regulatory environment that treated creator income as legitimate self-employment income.
India has pieces of this stack. It does not have the stack.
YouTube operates in India but with the CPM gap that makes vernacular content economically marginal. Instagram operates in India but does not pay creators; it uses them as free content generators. The indigenous platforms that rose during the TikTok ban in 2020 attracted volume but did not build the monetisation infrastructure that would have made creators economically dependent on them in a positive way.
The brand partnership marketplace is concentrated. The top few thousand creators in India's largest cities capture the overwhelming majority of brand deal value. The other 49 million creators are effectively invisible to the brand partnership economy.
What the 600 million represent
India has approximately 600 million people who primarily consume content in languages other than Hindi or English. Marathi, Tamil, Telugu, Kannada, Bengali, Odia, Punjabi, Bhojpuri, Rajasthani, and dozens more.
This is not a niche. This is the majority of India's internet users as they actually exist, not as the startup ecosystem imagines them.
The creator community serving this audience is enormous. It is also almost entirely outside the monetised creator economy. The infrastructure was not built with them in mind.
The inflection point comparison
The Indian ecommerce market in 2015 was at an interesting moment. The fundamentals were strong: a large population, growing smartphone penetration, improving payment infrastructure. But the ecommerce economy was a fraction of what it would become. The infrastructure was beginning to connect.
The Indian creator economy in 2025 is at a comparable moment. The fundamentals are stronger than they were in ecommerce in 2015: the content creation behaviour is already established, the audience engagement is already real, the device penetration is already there. What is missing is the monetisation infrastructure.
When ecommerce infrastructure clicked in India, it produced companies like Flipkart, Meesho, Mamaearth, and the D2C ecosystem that followed. The creator economy infrastructure, when it clicks, will produce an equivalent wave of economic activity.
What MeTubez is building into this gap
MeTubez is a video platform built under Twenties Entertainment Pvt. Ltd. since 2019. We hold a WIPO PCT international patent on the core technology and a Government of India grant.
The design principle is not to build a better YouTube. It is to build a different kind of monetisation architecture: one where a creator earns from their first video, regardless of subscriber count, content language, or whether a global advertiser considers their audience premium.
The market is not the top 2,000 creators in Mumbai and Delhi. The market is the 50 million creators who are currently outside the monetised economy.
That market has never had infrastructure built specifically for it. That is exactly why it is an infrastructure opportunity rather than a competitive one.
If you are an investor or fund paying attention to the Indian digital economy and have not yet thought carefully about creator economy infrastructure, the numbers in this article are the reason to start.